Keeping track of brokerage accounts, retirement plans, and scattered payment methods gets messy fast, and the right organizer can mean the difference between a five-minute lookup and an hour of digging through drawers. After comparing the most practical options available this year, three stand out for different reasons. The When I Die planner earns my top spot because it solves the hardest version of this problem: documenting accounts and assets so someone else can actually find them. The Investments & Retirement Accounts Organizer binder is the best pick for ongoing household tracking, while the 365-Day Investment Planner suits investors who want a guided workbook rather than a passive record-keeper.

Get smart everyday buys delivered free — and shop member deals
- Fast, free delivery on millions of items
- Access to Prime Big Deal Days deals on October 6–7
- Prime Video, Amazon Music and more included
The central tradeoff in this category is breadth versus depth. Some of these products aim to capture everything your family might ever need, including payment methods and estate instructions, while others go narrow and detailed on portfolio tracking alone. A second tradeoff is structure versus flexibility: fill-in-the-blank formats are easier to complete but force you into someone else’s categories, whereas binders give you room to improvise at the cost of a little discipline. My ranking below reflects which products handle those tradeoffs most gracefully for the largest number of buyers.
Key Takeaways
- The When I Die planner (B0BVPMVRMK) ranks highest because estate documentation is the highest-stakes use case for an account organizer, and it handles it with a clear fill-in-the-blank structure.
- The Investments & Retirement Accounts Organizer (B0GV49VYLJ) is the best everyday tracking tool, with dedicated sections for accounts, contributions, and holdings in a large-print format.
- The 365-Day Investment Planner (B0DBF54W43) is the only option here built for daily engagement rather than passive record-keeping, making it better for habit-building than for reference.
- Large print is a recurring strength across these picks, but every option is a manual paper system, so all of them require periodic updates to stay accurate.
- Buyers should choose based on who will eventually read the organizer: yourself, your spouse, or your heirs, since that determines whether breadth or depth matters more.
| When I Die: Planner and Organizer for Accounts and Assets | 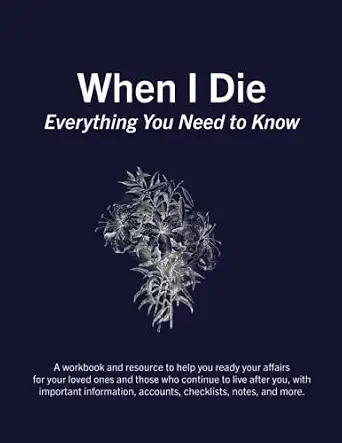 | Best Overall | Format: Fill-in-the-blank planner | Primary purpose: Estate planning and asset organization | Coverage: Accounts, assets, final wishes, probate guidance | VIEW LATEST PRICE | See Our Full Breakdown |
| Investments & Retirement Accounts Organizer: Large Print Family Finance Binder |  | Best for Ongoing Household Tracking | Format: Binder | Print size: Large print | Tracking sections: Accounts, contributions, holdings, notes | VIEW LATEST PRICE | See Our Full Breakdown |
| Investment Planner: Your 365-Day Guide to Smart Investing and Portfolio Management |  | Best Guided Workbook for Active Investors | Format: Planner/workbook | Duration: 365 days | Asset classes covered: Stocks, bonds, real estate, and more | VIEW LATEST PRICE | See Our Full Breakdown |
| Bank Accounts & Payment Methods Organizer |  | Best for Whole-Finances Breadth | Type: Home and family binder | Format: Large print | Coverage: Account numbers, cards, payment methods, contacts, notes | VIEW LATEST PRICE | See Our Full Breakdown |
| My Asset And Account Organizer |  | Budget-Simple Entry Point | Type: Asset and account organizer | Format: Unspecified | Coverage: Assets and accounts (general) | VIEW LATEST PRICE | See Our Full Breakdown |
| investment account organizer | Format | ASIN | Update expectation | Coverage |
|---|---|---|---|---|
| When I Die: Planner and Organi | Fill-in-the-blank planner | B0BVPMVRMK | Periodic, when accounts or assets change | Accounts, assets, final wishes, probate guidance |
| Investments & Retirement Accou | Binder | B0GV49VYLJ | Ongoing, as contributions and holdings change | — |
| Investment Planner: Your 365-D | Planner/workbook | B0DBF54W43 | Daily or weekly engagement | — |
| Bank Accounts & Payment Method | Large print | B0GPX4K6QB | Occasional, as accounts and cards change | Account numbers, cards, payment methods, contacts, notes |
| My Asset And Account Organizer | Unspecified | B0FNCCTXTS | — | Assets and accounts (general) |
More Details on Our Top Picks
When I Die: Planner and Organizer for Accounts and Assets
This planner takes the top spot because it attacks the most consequential version of account organization: making sure your accounts and assets are findable by the people who will need them after you are gone. The fill-in-the-blank format does quiet but powerful work here. Compared with the Investments & Retirement Accounts Organizer, which assumes you will be the one reading your own records for years to come, this planner is written for a second audience from the first page, covering final wishes and probate guidance alongside raw account data.
What makes it rank above everything else is completeness with guidance. Most organizers hand you blank pages and wish you luck. This one walks you through what to document, which matters enormously for buyers who find estate planning intimidating and would otherwise procrastinate. The probate and final-instructions sections give it a scope none of the other four picks attempt, and that scope is exactly what the title of this roundup demands: a true organizing system for investment accounts and the assets around them.
The tradeoff is maintenance. Because it captures a snapshot of your accounts, it needs periodic revisiting as you open new accounts, close old ones, or shift holdings. Buyers wanting a living document they update monthly will get more mileage from the binder-style pick below, and anyone hoping for daily portfolio reflection should look at the 365-day planner instead. But for a single, high-stakes document that consolidates everything in one guided pass, this is the strongest option in the lineup.
Pros:- Guided fill-in-the-blank structure removes guesswork about what to document
- Covers accounts, assets, final wishes, and probate guidance in one place
- Written with a second reader in mind, unlike most self-tracking organizers
- Reduces the burden on family members during an already difficult time
Cons:- Requires periodic updates as accounts and assets change
- Not designed for ongoing investment analysis or daily tracking
- Paper format means it should be stored somewhere secure and known to family
Best for: Anyone who wants a guided, one-pass system for documenting accounts, assets, and final wishes for their family or executor
Not ideal for: Investors who want a frequently updated tracker for day-to-day portfolio decisions
- Format:Fill-in-the-blank planner
- Primary purpose:Estate planning and asset organization
- Coverage:Accounts, assets, final wishes, probate guidance
- Intended reader:Family members and executors
- Update expectation:Periodic, when accounts or assets change
- Skill level:Beginner-friendly
- ASIN:B0BVPMVRMK
Our verdict“The most complete and purposeful organizer in this lineup, built for the scenario where accurate records matter most.”
Investments & Retirement Accounts Organizer: Large Print Family Finance Binder
If the top pick is a document you complete once and revisit occasionally, this binder is the opposite: a living record you keep adding to. Its structure splits cleanly into sections for accounts, contributions, holdings, and notes, which mirrors how retirement and brokerage money actually accumulates over time. That segmentation is what earns it the runner-up position. Compared with the When I Die planner, it trades estate guidance for day-to-day utility, and for households still actively building wealth, that trade is the right one.
The large-print format deserves more credit than it might seem to merit. Financial entries involve long account numbers and institution names, and larger fields reduce transcription errors while making the binder usable for older family members who may share responsibility for household finances. The family-finance framing also means it consolidates records for more than one person, which the single-user 365-day planner does not attempt.
The honest drawback is that a physical binder demands manual discipline. Nothing reminds you to log a contribution, and sparse listing details mean buyers are trusting the section layout sight-unseen to some degree. Anyone who wants prompts, structure, and built-in motivation will prefer the guided planner further down this list. This pick makes the most sense for disciplined households that want a permanent, no-subscription, screen-free reference that survives software changes and password lockouts.
Pros:- Dedicated sections for accounts, contributions, holdings, and notes
- Large print reduces errors and suits multi-generational use
- Consolidates family financial records in a single physical location
- No software, subscriptions, or digital access required
Cons:- Manual updates require self-discipline
- Limited product detail available on the listing
- Binder format is bulkier than a workbook if storage space is tight
Best for: Households that want a durable central binder for tracking multiple investment and retirement accounts over time
Not ideal for: People who need external structure and prompts to maintain a tracking habit
- Format:Binder
- Print size:Large print
- Tracking sections:Accounts, contributions, holdings, notes
- Household scope:Family-wide
- Update expectation:Ongoing, as contributions and holdings change
- Storage:Physical shelf storage
- ASIN:B0GV49VYLJ
Our verdict“The best choice for households that will actually maintain a tracker rather than complete one and shelve it.”
Investment Planner: Your 365-Day Guide to Smart Investing and Portfolio Management
This is the most ambitious product in the lineup conceptually: instead of recording what you own, it structures how you invest across a full year. The 365-day framing turns organization into a habit, with coverage spanning stocks, bonds, real estate, and additional asset classes. That breadth earns it a clear role that neither the estate planner nor the household binder fills. Where the binder asks “what accounts do you have,” this workbook asks “what are you doing with them this week.”
For investors trying to build discipline, that difference matters. Logging thoughts, decisions, and portfolio positions regularly creates a written record of your reasoning, which is genuinely useful when you want to understand why you made a move six months earlier. Compared with the When I Die planner, this is a self-focused tool: the audience is you, not your heirs. Compared with the binder, it covers more asset variety but less household breadth, since it is fundamentally a single-investor workbook.
Two caveats temper my enthusiasm. The listing offers no descriptive content to verify quality, so buyers are betting on the concept rather than confirmed execution, and a 365-day commitment is easy to abandon by February. This option stands out for motivated self-directed investors who already know they will use it; anyone buying discipline rather than supporting it should skip this and choose the simpler binder instead.
Pros:- Full-year structure supports habit-building around portfolio management
- Covers multiple asset classes including stocks, bonds, and real estate
- Creates a written record of investment decisions and reasoning
- Guided format reduces the blank-page problem of unstructured notebooks
Cons:- No description or review content available to verify quality
- Requires sustained daily engagement that many buyers will not maintain
- Focused on one investor rather than a whole household
Best for: Self-directed investors who want a daily and weekly workbook to build consistent portfolio-management habits
Not ideal for: Buyers who want a low-maintenance reference document or passive record of accounts
- Format:Planner/workbook
- Duration:365 days
- Asset classes covered:Stocks, bonds, real estate, and more
- Intended user:Individual self-directed investor
- Update expectation:Daily or weekly engagement
- Skill level:Intermediate
- ASIN:B0DBF54W43
Our verdict“The right pick only for investors who will genuinely work through a year-long guided workbook.”
Bank Accounts & Payment Methods Organizer
This organizer earns its place by going widest of any pick here. Rather than focusing on investments alone, it captures bank accounts, cards, payment methods, and contacts in one large-print home binder. For a buyer whose financial life is scattered across checking accounts, credit cards, and investment accounts, that breadth is exactly the point: one place to look up any institution you do business with.
Positioned against the Investments & Retirement Accounts Organizer, the difference is emphasis. That binder digs into contributions and holdings; this one prioritizes account access and payment logistics. They are closer cousins than any other two picks in this roundup, and choosing between them comes down to whether you need portfolio detail or whole-finances coverage. A household could reasonably own both and let each do its job, but if forced to pick one, active investors get more from the retirement-focused binder.
The weakness is that breadth dilutes depth. Do not expect granular holdings tracking or any investment-specific structure, and the listing offers little detail to confirm exactly how the sections are laid out. This model is better suited to acting as the family’s master index of financial relationships, and it works well paired with a more specialized tool. Solo investors who only hold a brokerage account and a retirement plan will find it underutilized.
Pros:- Large print format makes entries easy to read and write
- Centralizes accounts, cards, and contacts in one accessible binder
- Breadth suits households with many financial relationships
- Works well as a companion to a more investment-focused organizer
Cons:- Shallow on investment-specific detail like holdings and contributions
- No detailed product information available
- Overkill for someone with only one or two accounts
Best for: Families who want a master index of every bank account, card, and payment method alongside their investments
Not ideal for: Investors who need detailed holdings and contribution tracking
- Type:Home and family binder
- Format:Large print
- Coverage:Account numbers, cards, payment methods, contacts, notes
- Household scope:Family-wide
- Update expectation:Occasional, as accounts and cards change
- Investment depth:Basic
- ASIN:B0GPX4K6QB
Our verdict“The broadest net in the lineup, best treated as a household master index rather than an investment tracker.”
My Asset And Account Organizer
Ranking last is less a judgment of quality than an honest response to what is knowable. This listing provides almost no product detail, which makes it impossible to verify format, structure, or scope the way I could with the other four picks. What can be said is that its title positions it squarely in the core organizing niche: a general-purpose place to record assets and accounts, presumably in a simple fill-in format.
Compared with the rest of the lineup, its likely appeal is simplicity and price sensitivity. If it follows the standard formula for products of this type, it will offer basic account-listing pages without the estate guidance of the When I Die planner, the household sections of the retirement binder, or the year-long structure of the 365-day workbook. For a buyer who wants a minimal place to write down accounts without paying for features they will not use, that plainness may be exactly right.
I cannot in good conscience rank it higher while its contents remain a question mark. Buyers willing to accept some uncertainty in exchange for a simple, low-commitment entry point may find it adequate, but anyone who wants to know exactly what they are getting should choose the top pick, which documents its full scope clearly. Treat this as the budget fallback of the group rather than a first choice.
Pros:- Covers the core job of listing assets and accounts in one place
- Simple concept with no learning curve
- Likely a low-cost entry point into organized record-keeping
- Compact scope suits first-time organizers
Cons:- Insufficient product information available to verify format or quality
- No documented guidance, sections, or special features
- Likely outclassed by better-documented picks at each specific job
Best for: Buyers who want a basic, no-frills place to list accounts and assets at minimal cost
Not ideal for: Anyone who needs to know exactly what structure and sections they are buying before ordering
- Type:Asset and account organizer
- Format:Unspecified
- Coverage:Assets and accounts (general)
- Guidance level:Unknown
- Household scope:Unspecified
- Documentation available:Minimal
- ASIN:B0FNCCTXTS
Our verdict“A leap-of-faith pick whose thin listing keeps it at the bottom despite a promising premise.”
How We Picked
Since every product in this category is a paper-based organizer, I judged them on what actually separates a useful financial binder from one that ends up half-filled in a drawer. The first criterion was structural clarity: does the product give a buyer logical places to record account numbers, institutions, holdings, and instructions, or does it leave too much to the imagination? Products with explicit sections for contributions, contacts, or final wishes scored higher than vague catch-all notebooks.
The second criterion was intended audience. Some organizers are written for the person filling them out, while others are written for the spouse, adult child, or executor who will read them later. I weighted products that acknowledged this second reader more heavily, because that is where organized financial records deliver their greatest value. The third criterion was usability over time, including print size, update-friendliness, and whether the format invites regular maintenance or one-time completion. Finally, I factored in information transparency: several listings offer thin detail, and I flagged that honestly rather than guessing at quality. Where a product’s documentation is sparse, I said so, because a buyer deserves to know what they can and cannot verify before ordering.
| investment account organizer | Format | Coverage | Update expectation | ASIN |
|---|---|---|---|---|
| When I Die: Planner and Organi | Fill-in-the-blank planner | Accounts, assets, final wishes, probate guidance | Periodic, when accounts or assets change | B0BVPMVRMK |
| Investments & Retirement Accou | Binder | — | Ongoing, as contributions and holdings change | B0GV49VYLJ |
| Investment Planner: Your 365-D | Planner/workbook | — | Daily or weekly engagement | B0DBF54W43 |
| Bank Accounts & Payment Method | Large print | Account numbers, cards, payment methods, contacts, notes | Occasional, as accounts and cards change | B0GPX4K6QB |
| My Asset And Account Organizer | Unspecified | Assets and accounts (general) | — | B0FNCCTXTS |
Factors to Consider When Choosing Investment Account Organizers
Choosing among these organizers comes down to three questions: who will read it, how often you will update it, and how much structure you need. The sections below break down each decision point so you can match yourself to the right pick before buying.Passive Record vs. Active Workbook
The biggest fork in this category is between reference documents and working documents. The When I Die planner and both binders are reference documents: you fill them in, store them, and consult them when something needs looking up. The 365-Day Investment Planner is a working document that expects weekly or daily engagement. Reference organizers stay useful for years with minimal effort but go stale if ignored; workbooks stay current but only if you actually use them. Be honest about which habit you have before choosing.
Who the Organizer Is For
If the answer is only you, a workbook or a personal binder works fine. If the answer is your spouse, your children, or an executor, you need a product designed for a second reader, which is why the estate-focused planner ranks first in this roundup. Large-print formats, like those in the two binders here, also matter when older family members share financial responsibility, since legible entries reduce errors for every reader.
Breadth of Coverage
Ask what you actually need to record. Households with many bank accounts, credit cards, and payment methods get more from a broad binder like the Bank Accounts & Payment Methods Organizer. Investors tracking contributions, holdings, and retirement accounts get more from a deep tracker like the Investments & Retirement Accounts Organizer. Buyers trying to cover both should consider pairing two products rather than forcing one to do both jobs poorly.
Guidance Level
Fill-in-the-blank formats with prompts suit beginners who do not know what to document, while open binders suit experienced organizers who already have a system in mind. The estate planner offers the most guidance in this lineup; the generic organizers offer the least. If staring at blank pages has stopped you before, choose guidance over flexibility.
Maintenance Reality Check
Every product here is a paper system with no automatic updates. Accounts change, contributions land monthly, and holdings shift. Pick an update rhythm you can sustain, whether that is a quarterly review for a binder or a weekly session for a workbook, and store the finished organizer somewhere secure but findable by whoever needs it. An out-of-date organizer is often worse than none at all, because it projects false confidence.
Frequently Asked Questions
Are paper investment organizers still worth using when so much financial data is available online?
Paper organizers remain genuinely useful for one main reason: online access disappears exactly when it is needed most. If you are ill, traveling, or deceased, your family cannot log into your accounts without credentials they may not have, and password managers fail for the same reason. A physical organizer survives software changes, subscription lapses, and locked devices. It also cannot be hacked, requires no updates to an app, and can be grabbed off a shelf during an emergency. For most buyers, the strongest setup is a hybrid: use online tools for daily monitoring, and keep a paper organizer as the authoritative snapshot for accounts, institutions, and instructions.
How often should I update an investment account organizer?
For a reference binder or estate planner, a quarterly update rhythm works well for most households, paired with an immediate update whenever you open a new account, close an old one, or change institutions. You do not need to log every market move; what matters is that account names, institutions, and contact information stay accurate, because those are the details a family member or executor would need. For a daily workbook like the 365-day planner, the answer is built into the product: you update it as often as you engage with your portfolio, ideally weekly. A calendar reminder for a fixed quarterly review is the simplest way to keep a paper system from going stale.
Should I store real account numbers and passwords in one of these organizers?
Recording account numbers and institution names is the entire point of these products and is generally fine when the organizer is stored securely. Passwords and PINs are a different matter, and I would advise against writing them in any document that sits on a shelf. Instead, record where your passwords live, such as the name of a password manager, or note the location of a separate secure document, and make sure your spouse or executor knows how to reach it. Pair this with a locked drawer or fireproof box for the organizer itself, and mention its location to at least one trusted person, since a perfectly organized binder that nobody can find accomplishes nothing.
What is the difference between an investment organizer and an estate planner like the When I Die book?
An investment organizer is written for you: it helps you track accounts, contributions, and holdings so your own financial picture stays clear. An estate planner is written for someone else: it assumes the reader will be a spouse, adult child, or executor who needs to locate accounts, understand your wishes, and navigate probate. The two overlap heavily in the data they capture, but the framing differs, and that framing shapes everything from the section layout to the tone of the guidance. Households with both needs often do best owning one of each, or choosing the estate planner and using its account sections as their primary tracker.
Is a large-print format actually important, or just a niche feature?
Large print earns its place for practical reasons that go beyond eyesight. Financial entries involve long account numbers, institution names, and dollar figures, and bigger fields reduce transcription errors for every user, not just older ones. Large print also makes the binder usable by multiple household members, which matters when a spouse or parent needs to read entries you wrote months earlier. The tradeoff is space: larger print means fewer entries per page and a bulkier finished product. For a document intended to be read under stress, though, legibility wins that trade in my judgment, which is part of why two large-print picks rank near the top of this list.
Conclusion
After working through all five, my recommendations split cleanly by buyer type. If you want one document that covers everything your family would need if something happened to you, choose the When I Die planner; it is the most purposeful and complete option here. If you are a household actively building retirement wealth and want a tracker you will actually maintain, the Investments & Retirement Accounts Organizer binder is the better fit. Self-directed investors who enjoy the process of investing should get the 365-Day Investment Planner, with the honest caveat that it only pays off if used consistently.
Buyers whose financial lives are scattered across many banks, cards, and payment methods will get the most from the Bank Accounts & Payment Methods Organizer, ideally paired with a deeper investment tracker. And first-time buyers on a tight budget who just want somewhere simple to list accounts can try My Asset And Account Organizer, accepting that its thin listing makes it a modest gamble. Whatever you choose, the real win is the same across all five: moving your financial life out of your head and into a format someone, including future you, can actually use.
Fall Picks
fall essentials
As an affiliate, we earn on qualifying purchases.