If your investment accounts are scattered across brokerage statements, retirement portals, spreadsheets, and a few password-manager notes, an investment account organizer can pull everything into one place. After comparing the leading options on Amazon, I landed on three standouts. The Investments & Retirement Accounts Organizer binder earns my top spot for households that want a durable, large-print hub for every account a family holds. The Investment Planner: Your 365-Day Guide is the better fit for active investors who want a guided, day-by-day workbook rather than a static reference binder. And When I Die plays a different role entirely — it’s an estate-planning organizer built for the people who will manage your accounts after you’re gone. The main tradeoff in this category is simple: structure versus flexibility. A binder with pre-printed sections keeps records consistent but forces you into its format, while a workbook-style planner builds good habits but becomes obsolete the moment you stop filling it in. There’s also the question of who the organizer is actually for — you, or your heirs — and that distinction separates these four products more than any feature list.

Get smart everyday buys delivered free — and shop member deals
- Fast, free delivery on millions of items
- Access to Prime Big Deal Days deals on October 6–7
- Prime Video, Amazon Music and more included
Key Takeaways
- The Investments & Retirement Accounts Organizer binder is the best overall pick for families consolidating multiple investment and retirement accounts in one physical hub.
- The 365-Day Investment Planner is the only option here built for daily and weekly portfolio habits, covering stocks, bonds, and real estate across a full year.
- When I Die solves a different problem than the other three: it organizes accounts and assets so heirs and executors can find everything, not so you can track performance.
- My Asset And Account Organizer lacks published details on format and layout, making it the riskiest purchase of the four without further seller verification.
- All four are paper-based, so every pick requires manual updates — none syncs with brokerage accounts or replaces digital statements.
| Investments & Retirement Accounts Organizer: Large Print Family Finance Binder |  | Best Overall | Format: Physical binder | Print Size: Large print | Primary Use: Tracking accounts, contributions, holdings, and notes | VIEW LATEST PRICE | See Our Full Breakdown |
| Investment Planner: Your 365-Day Guide to Smart Investing and Portfolio Management |  | Best for Building Daily Habits | Format: Planner / workbook | Coverage Period: 365 days | Asset Types Covered: Stocks, bonds, real estate, and more | VIEW LATEST PRICE | See Our Full Breakdown |
| When I Die: Planner and Organizer for Accounts and Assets | 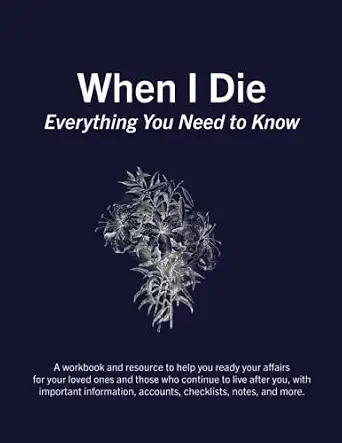 | Best for Estate Documentation | Format: Fill-in-the-blank planner | Purpose: Estate planning and asset organization | Primary Audience: Heirs, spouses, and executors | VIEW LATEST PRICE | See Our Full Breakdown |
| My Asset And Account Organizer |  | Budget Wildcard | Format: Not specified by seller | Primary Use: Asset and account documentation | Documented Sections: Not listed | VIEW LATEST PRICE | See Our Full Breakdown |
| investment account organizer | Format | ASIN | Primary Use | Maintenance |
|---|---|---|---|---|
| Investments & Retirement Accou | Physical binder | B0GV49VYLJ | Tracking accounts, contributions, holdings, and notes | Manual updates required |
| Investment Planner: Your 365-D | Planner / workbook | B0DBF54W43 | — | — |
| When I Die: Planner and Organi | Fill-in-the-blank planner | B0BVPMVRMK | — | Periodic updates needed as assets change |
| My Asset And Account Organizer | Not specified by seller | B0FNCCTXTS | Asset and account documentation | — |
More Details on Our Top Picks
Investments & Retirement Accounts Organizer: Large Print Family Finance Binder
This binder takes the top spot because it attacks the core problem of investment organization head-on: too many accounts, too many places. Where the 365-Day Planner is built around a calendar, this organizer is built around your actual holdings. Dedicated sections for accounts, contributions, holdings, and notes mean every brokerage, IRA, 401(k), and taxable account a household owns can live in one physical location, and anyone in the family can find it.
The large-print format is the quiet differentiator here. Compared with the smaller workbook layouts typical of planners like the 365-Day Guide, larger type makes a real difference for anyone who fills in balances under less-than-ideal lighting, or for older spouses and relatives who may need to reference the binder later. That accessibility angle is also what makes it a better household record-keeper than the When I Die planner, which is optimized for heirs rather than for ongoing personal use.
The tradeoff is that this is a manually maintained system. It doesn’t update itself, and a binder full of account details ages fast if you don’t commit to regular entries — a limitation it shares with every paper product in this lineup, but one that stings more here because the binder’s value is as a current snapshot. The listing also offers little descriptive detail about page count or cover material, so there’s some uncertainty about exactly what arrives. Still, for the most common job — consolidating a family’s investment records into one readable, structured place — this option makes the most sense of the four.
Pros:- Large print makes entries easy to read and write, which matters for shared household use
- Structured sections for accounts, contributions, and holdings keep records consistent
- Consolidates an entire family’s financial records in one physical location
- Binder format lets you add, remove, or reorder pages as accounts change
Cons:- Entirely manual — requires discipline to keep balances and holdings current
- Listing provides minimal product detail, so page count and materials are unverified
Best for: Households and families who want a single, readable physical hub for tracking multiple investment and retirement accounts
Not ideal for: Active investors who want daily or weekly planning prompts, or anyone expecting automatic syncing with brokerage accounts
- Format:Physical binder
- Print Size:Large print
- Primary Use:Tracking accounts, contributions, holdings, and notes
- Household Suitability:Designed for family-wide financial records
- Maintenance:Manual updates required
- Guidance Level:Structured sections, not a coached curriculum
- ASIN:B0GV49VYLJ
Our verdict“The most practical all-around choice for turning a scattered mess of investment accounts into one organized, family-accessible record.”
Investment Planner: Your 365-Day Guide to Smart Investing and Portfolio Management
Where the top pick is a reference binder, this planner is a coached program. Its 365-day structure turns portfolio management from a chore you do quarterly into a habit you practice daily and weekly, which is a fundamentally different value proposition. For investors who know they should review allocations regularly but never do, a dated format creates the kind of gentle accountability a plain binder can’t match.
The other strength is breadth of asset coverage. Tracking sections for stocks, bonds, and real estate in one workbook mean you’re not forced to maintain parallel systems for different asset classes — something the Investments & Retirement Accounts Organizer handles with generic sections but doesn’t frame around asset types. If your portfolio spans a brokerage account, some bond holdings, and a rental property, this planner gives each a home within a single yearly framework.
The obvious weakness is the calendar itself. A 365-day planner has a shelf life of exactly one year; miss two months and you’re left with blank dated pages that make the book feel stale, unlike the undated binder, which stays current as long as you keep writing in it. It’s also more of a commitment — this product suits someone who genuinely wants to work on their investing process, not someone who just wants their account numbers written down somewhere. The listing lacks verified detail on page quality and internal layout, so there’s some purchase risk, but the concept is the strongest of the four for disciplined, engaged investors.
Pros:- Full-year coverage builds a genuine portfolio-management routine
- Covers stocks, bonds, real estate, and other asset classes in one place
- Guided format teaches investing discipline rather than just storing data
- Better suited to active decision-making than static record-keeping
Cons:- Dated format expires — blank pages after a skipped period make the book feel unusable
- No verified review content or detailed listing information to confirm quality
Best for: Self-directed investors who want daily and weekly structure to build consistent portfolio-review habits across multiple asset classes
Not ideal for: Anyone seeking a simple, set-and-forget record of account details, or people unlikely to maintain a dated daily format
- Format:Planner / workbook
- Coverage Period:365 days
- Asset Types Covered:Stocks, bonds, real estate, and more
- Structure:Dated, guided daily and weekly entries
- Skill Level:Best for engaged, self-directed investors
- Longevity:One year per book
- ASIN:B0DBF54W43
Our verdict“The right choice if your goal is changing how you manage money over a year, not just documenting where it sits today.”
When I Die: Planner and Organizer for Accounts and Assets
This pick earns its place by solving the problem the other three ignore: what happens to your accounts when you can’t explain them yourself. It’s a fill-in-the-blank planner where you record accounts, assets, passwords-adjacent details, final wishes, and instructions — essentially a handoff document for spouses, adult children, or executors. That makes it less a competitor to the top two picks and more a complement to them.
Compared with the Investments & Retirement Accounts Organizer, this planner sacrifices tracking structure for end-of-life completeness. Where the binder helps you monitor contributions and holdings over time, When I Die helps someone else locate and settle those same holdings. The fill-in-the-blank format lowers the effort barrier considerably — you’re answering prompts, not designing a system — which is why it works well for people who find estate planning overwhelming. The probate and final-instructions guidance also adds a coaching layer the other products don’t attempt.
The real drawback is decay. An estate organizer is a snapshot, and snapshots go stale: open a new account, move a brokerage, refinance a property, and the document is quietly wrong until you update it. Unlike the binder, whose sections invite regular revision, this planner is typically filled in once and revisited rarely — exactly when errors creep in. It also does nothing for day-to-day portfolio management, so anyone buying it expecting an investment tracker will be disappointed. As a single-purpose estate tool, though, it fills a gap none of the other three address.
Pros:- Consolidates accounts, assets, and final wishes in a single document loved ones can find
- Fill-in-the-blank format makes estate planning approachable without a lawyer’s help
- Includes practical guidance on probate and final instructions
- Complements a tracking binder rather than duplicating it
Cons:- Becomes outdated as accounts and assets change, requiring periodic re-checking
- Not designed for performance tracking or contribution monitoring
Best for: Adults of any age who want a simple, guided way to document accounts, assets, and final wishes for their family and executors
Not ideal for: Anyone looking for ongoing investment tracking, contribution logging, or portfolio-management structure
- Format:Fill-in-the-blank planner
- Purpose:Estate planning and asset organization
- Primary Audience:Heirs, spouses, and executors
- Guidance Included:Probate and final-instructions direction
- Maintenance:Periodic updates needed as assets change
- Tracking Capability:Documentation only, no portfolio management
- ASIN:B0BVPMVRMK
Our verdict“An essential companion purchase rather than a replacement — it documents your accounts for others instead of tracking them for yourself.”
My Asset And Account Organizer
I’ll be direct about this one: My Asset And Account Organizer arrives with almost no verified information — no format details, no layout description, no stated section structure. That makes it the hardest of the four to recommend confidently, but also worth discussing honestly, because budget-priced organizers sometimes deliver exactly what the bigger names do with less polish.
Based on its title, it appears aimed at the same job as the top pick — a general organizer for assets and accounts — which would put it in direct competition with the Investments & Retirement Accounts Organizer binder. If it delivers a comparable structure, it could appeal to buyers who want a second copy for a vacation home, a safety deposit box, or a duplicate for another household member, without paying for the flagship’s large-print family formatting. Its likely role is as a low-commitment spare or starter, not a primary system.
Compared with every other product here, though, the information gap is a real risk. The When I Die planner tells you exactly what it does; the 365-Day Guide tells you its coverage and asset scope; this listing tells you almost nothing. My suggestion: check the seller’s images and any updated listing details before buying, and treat it as a supplement to one of the more documented picks rather than your only organizer. If it turns out to be a well-structured log, you’ve saved money; if not, you’ve learned why detailed listings matter.
Pros:- Covers the same core job — listing assets and accounts — as pricier organizers
- Potentially useful as a duplicate copy kept in a second location
- Low-risk way to test whether a paper organizer works for you
Cons:- Almost no product information available to verify format or quality
- No documented section structure, so layout may not match your needs
Best for: Buyers wanting an inexpensive secondary or duplicate organizer, or those willing to gamble on an undocumented format after checking seller images
Not ideal for: Anyone who needs to know exactly what they’re getting before it arrives
- Format:Not specified by seller
- Primary Use:Asset and account documentation
- Documented Sections:Not listed
- Best Role:Secondary or duplicate organizer
- Information Available:Minimal listing detail
- ASIN:B0FNCCTXTS
Our verdict“A reasonable gamble as a backup organizer, but not a system to build your financial record-keeping around.”
How We Picked
I judged each organizer against what actually matters when you’re trying to bring order to investment accounts. The first criterion was structure: does the product give you a clear framework for recording accounts, balances, contributions, and holdings, or does it leave you staring at blank pages? The second was scope — some organizers are built for ongoing portfolio tracking, others for one-time documentation, and matching the product to the job matters more than any single feature. Third, I weighed usability, including print size, layout clarity, and how easy the format is to maintain over months and years. A large-print binder a retiree can actually read beats an elegant workbook nobody fills in. Fourth, I considered documentation quality: how much verified information the listing provides, since vague listings make it hard to know what you’re buying. Finally, I looked at durability of the system itself — whether the organizer stays useful as accounts change, or whether it becomes a snapshot that ages poorly. No single product wins every criterion, and I’ve been explicit about where each one falls short.
| investment account organizer | Format | Primary Use | Maintenance | ASIN |
|---|---|---|---|---|
| Investments & Retirement Accou | Physical binder | Tracking accounts, contributions, holdings, and notes | Manual updates required | B0GV49VYLJ |
| Investment Planner: Your 365-D | Planner / workbook | — | — | B0DBF54W43 |
| When I Die: Planner and Organi | Fill-in-the-blank planner | — | Periodic updates needed as assets change | B0BVPMVRMK |
| My Asset And Account Organizer | Not specified by seller | Asset and account documentation | — | B0FNCCTXTS |
Factors to Consider When Choosing Investment Account Organizers
Before choosing an investment account organizer, it helps to understand what separates these products and which factors should drive your decision. Here’s what I’d weigh most heavily.Purpose: Tracking, Planning, or Handoff?
These four organizers split into three distinct jobs. Trackers like the Investments & Retirement Accounts Organizer binder record where your accounts and holdings sit today. Planners like the 365-Day Guide coach you through managing those holdings over time. Handoff documents like When I Die organize information for someone else after you can’t. Buying the wrong type is the most common mistake — an estate planner won’t help you review allocations, and a daily planner won’t help your executor find your brokerage accounts. Ideally, serious households eventually own one of each type.
Format and Maintenance
Binders are forgiving: pages can be updated, reordered, and added to, which keeps the system alive as your accounts change. Dated planners create strong habits but expire — a half-filled 365-day book is a sunk commitment. Fill-in-the-blank estate documents sit somewhere between, typically filled in once and revisited occasionally. Ask yourself honestly how often you’ll update the thing; the best organizer is the one you’ll actually maintain, not the one with the most features.
Readability and Shared Access
If more than one person will use the organizer — a spouse, an adult child, an executor — large print and clear layout become genuine features rather than luxuries. The large-print binder wins on this dimension; dense workbook layouts can be hard for older relatives to use. Think about who needs to read your records in five years, not just who writes them today.
Asset Coverage
Investors with straightforward portfolios — a 401(k) and one brokerage account — can use almost any organizer. But if you hold real estate, bonds, or multiple retirement vehicles, look for products that explicitly structure those asset classes, as the 365-Day Guide does. Generic sections work, but purpose-built ones reduce the chance that important holdings fall through the cracks.
Paper Versus Digital
Every product here is paper-based, and that comes with real tradeoffs. Paper survives tech failures, works during power outages, and is easy for heirs to find — but it never syncs with your brokerage and can lag reality. Many households run a hybrid: a spreadsheet or app for live tracking, plus a paper organizer as the authoritative physical record. If that’s your plan, buy the paper product for durability and clarity, not for automation it can’t provide.
Frequently Asked Questions
What is an investment account organizer, and do I actually need one?
An investment account organizer is a structured physical system — usually a binder or workbook — for recording your investment and retirement accounts, balances, contributions, and holdings in one place. Whether you need one depends on how scattered your finances are. If you have more than two or three accounts across different institutions, or if a spouse or family member would struggle to locate everything in an emergency, an organizer earns its keep quickly. If you hold a single 401(k) and check it monthly, you may get by with a simple spreadsheet. The strongest argument for a paper organizer is resilience: it doesn’t depend on passwords, platforms, or subscription services still existing when someone needs it.
Should I choose a binder or a dated planner format?
The choice comes down to how you’ll use it. A binder like the Investments & Retirement Accounts Organizer works best as a living reference — you update it whenever accounts change, and it stays useful indefinitely. A dated planner like the 365-Day Guide works best as a habit-building tool, giving you daily and weekly prompts to engage with your portfolio. If you’re disciplined about reviews but your records are a mess, get the binder. If your records are fine but your engagement is spotty, the planner’s structure will do more for you. Be honest about your follow-through: a dated planner with blank pages is worse than no planner at all.
Can an investment organizer replace a will or estate attorney?
No, and it’s worth being clear about that boundary. Products like When I Die help you document and organize — where accounts are held, what assets exist, what your wishes are — which genuinely reduces the burden on your heirs and can simplify probate. But a planner has no legal force. Wills, trusts, powers of attorney, and beneficiary designations do the legal work, and an organizer merely points to them. The best approach is to pair proper legal documents with a well-maintained organizer so your executor knows both what you wanted and where everything is.
How often should I update a paper investment organizer?
For a tracking binder, a quarterly update cycle is realistic for most people — aligned with when quarterly statements arrive — with an annual full review at tax time. Estate organizers should be reviewed at least once a year and immediately after major life events: opening or closing accounts, moving, marriage, divorce, a new property, or a death in the family. The biggest risk with any paper system is silent staleness, so I’d suggest writing the last-updated date on the cover or first page. If a loved one picks up the organizer and sees it hasn’t been touched in three years, they’ll rightly distrust everything inside it.
Is it safe to write all my account details in a physical organizer?
A physical organizer is safest when you record where accounts exist and who to contact without writing down actual passwords or full account numbers. List the institution, the account type, the approximate value, and your advisor’s phone number — enough for an authorized person to locate and access the account through proper channels. Store the organizer somewhere secure but findable, like a locked drawer your spouse or executor knows about, and never leave it somewhere visible to visitors. If you do record sensitive numbers, that’s an argument for keeping the organizer in a fireproof safe alongside your other key documents, and for updating it if it ever leaves your control.
Conclusion
My recommendations break down cleanly by buyer type. If you’re a household manager trying to consolidate a family’s investment and retirement accounts into one readable place, buy the Investments & Retirement Accounts Organizer binder — it’s the most versatile and most maintainable pick of the four. If you’re an engaged, self-directed investor who wants to build better portfolio habits across stocks, bonds, and real estate, the 365-Day Investment Planner gives you the guided structure a static binder can’t. If you’re planning your estate or want to spare your family a frantic document hunt, When I Die is purpose-built for that handoff and pairs well with either of the first two. And if you just want an inexpensive spare or a low-stakes test of paper organizing, My Asset And Account Organizer can fill that role — after you verify its layout from the seller’s listing. The strongest setup, for what it’s worth, is combining a tracker with an estate document: one keeps your records current, the other makes sure they survive you.
Fall Picks
fall essentials
As an affiliate, we earn on qualifying purchases.